Introduction to Mortgage Calculators
A home loan in Dubai costs more than the monthly instalment. On a AED 1.5 million flat with a 20% deposit, a AED 1.2 million loan at 3.9% over 25 years is about AED 6,270 a month, and you need roughly AED 382,000 in cash on day one: the deposit, the 4% DLD fee, and bank and registration charges. Service charges and insurance come on top each month.
To calculate the payment yourself, enter the loan amount (the property price minus your down payment), the interest rate and the loan term, up to 25 years, into a mortgage calculator such as our mortgage calculator. That gives you principal and interest only, so add the other costs below before you decide what you can afford.
A calculator helps you compare lenders and loan options before you commit, and it works just as well if you are weighing a refinance. If you are considering one, see our guide to transferring a mortgage in Dubai.
Banks set terms by looking at the loan amount, interest rate, tenure, your income and existing debts. They also apply the loan-to-value (LTV) ratio, the share of the price the bank will lend. For a resident expat buying a first home, the UAE Central Bank allows up to 80% LTV on properties up to AED 5 million and 70% above that. A second home is capped at 60% and off-plan purchases at 50%.
The Real Cost of Homeownership in Dubai
Buying a home in Dubai is a dream for many, whether it’s a sleek apartment in Downtown, a villa in Arabian Ranches, or a family-friendly community in Mirdif. But beyond the glossy brochures and stunning show units lies something more important: realistic financial planning.
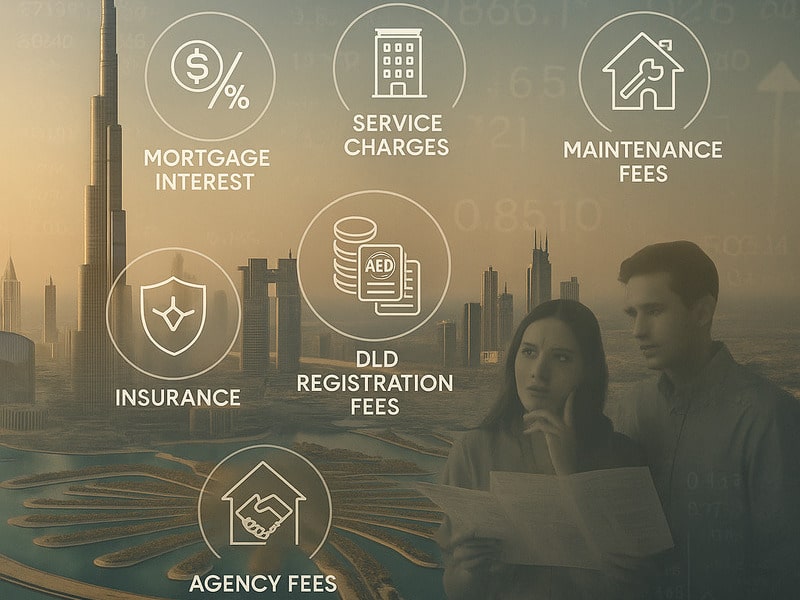
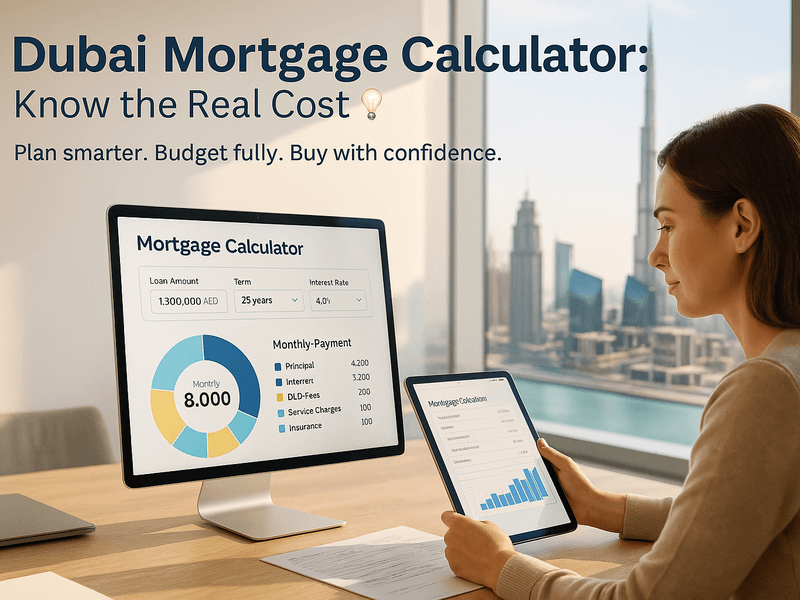
Too many buyers use a basic mortgage calculator Dubai, looking only at principal and interest. But that’s not enough. If you’re planning to buy property in Dubai, you need to understand the full picture, including fees, insurance, and service charges. Let’s break it down.
Understanding Home Loans
A home loan, also known as a mortgage loan, is a financial product used to purchase property. When you take out a home loan, you receive a loan amount that you repay over time through monthly mortgage payments. These payments typically include both principal and interest. The interest rate on a home loan can be either fixed or variable, depending on the mortgage type.
Fixed-rate mortgages offer stability with a consistent interest rate throughout the loan term, while variable-rate mortgages feature fluctuating interest rates based on market conditions. See our full comparison of fixed vs variable mortgage rates in Dubai for a closer look at which suits your situation. The loan term, or repayment period, can range from 10 to 25 years, depending on the lender and your affordability. The UAE offers various mortgage options, including fixed-rate and variable-rate mortgages, as well as Sharia-compliant Islamic mortgages, to suit different needs and budgets.
Why the Right Mortgage Calculator Matters
A standard home loan calculator Dubai gives you an estimate of your monthly payment based on:
- Loan amount
- Interest rate
- Loan term
But it often misses key monthly costs like:
- Property-related fees (DLD, Municipality Housing Fee, Registration)
- Service charges (maintenance)
- Home & life insurance
To get the full picture, you need a mortgage loan calculator Dubai that accounts for all of these. Various tools, including a comprehensive mortgage calculator, can help you get an accurate estimate of your monthly payments. Otherwise, you risk underestimating your monthly commitment, and that can be costly.
What’s Included in a Complete Mortgage Payment in Dubai?
1. Principal & Interest
The principal is the amount you borrow. The interest, determined by the mortgage rate, is what the bank charges you to borrow it.
Tip: Choose between:
- Fixed-rate mortgage: Stable monthly payments
- Variable-rate mortgage: Lower initial rate, but subject to change
As of 2026, fixed bank mortgage rates in Dubai run roughly 3.75% to 5% per annum, tracking the UAE Central Bank's base rate (3.9% since mid-September 2026) and the 3-month EIBOR (around 4%), and varying with your credit score, income, and mortgage broker Dubai.
2. Property Fees: Dubai’s Hidden “Tax”
While there’s no annual property tax in Dubai, there are still significant government-related costs:
| Fee | Amount |
|---|---|
| DLD Fee (some buyers may qualify for a DLD fee waiver) | 4% of property value (one-time) |
| Registration Fee | AED 2,000 to 4,000 + VAT |
| Mortgage Registration (DLD) | 0.25% of the loan + AED 290 (one-time) |
| Bank Processing Fee | Usually 0.5% to 1% of the loan, sometimes waived in promotions |
| Valuation Fee | AED 2,500 to 3,500 |
| Municipality Housing Fee | 5% of property’s annual rental value (monthly via DEWA) |
| Service Charges | AED 3 to 30/sq.ft annually |
Buyers normally pay the one-time fees in cash, on top of the deposit. Use the Dubai Land Department’s Service Charge Index to estimate service fees. If you use an agent, commission is typically 2% of the price plus VAT, and a registered broker can explain each line before you commit.
3. Insurance: Don’t Skip This Step
Lenders usually require:
- Building insurance
- Life insurance (aka mortgage protection)
Optional but wise:
- Contents insurance for your belongings
Costs range from AED 250/year to 0.5% of rebuild value, and can vary depending on your property type and insurer.
Understanding Loan Period
The loan period, also known as the loan term, is the length of time over which the loan is repaid. This period can range from 10 to 25 years, depending on the lender and your financial situation. A longer loan period may result in lower monthly payments, but it can also increase the total amount paid over the life of the loan. Conversely, a shorter loan period may lead to higher monthly payments but reduce the overall cost of the loan.
The term has a large effect on what you pay. On a AED 1.2 million loan at 3.9%, a 25 year term costs about AED 6,270 a month and about AED 680,000 in total interest.
Factors Affecting Mortgage
Several factors shape what you pay: the property value, the down payment, the mortgage amount, the interest rate and the loan duration. The mortgage amount is the sum left after the down payment. Existing debts, income and credit score also count, and lenders adjust their rates and terms as market conditions change.
Escrow Accounts: Simplify Your Monthly Costs
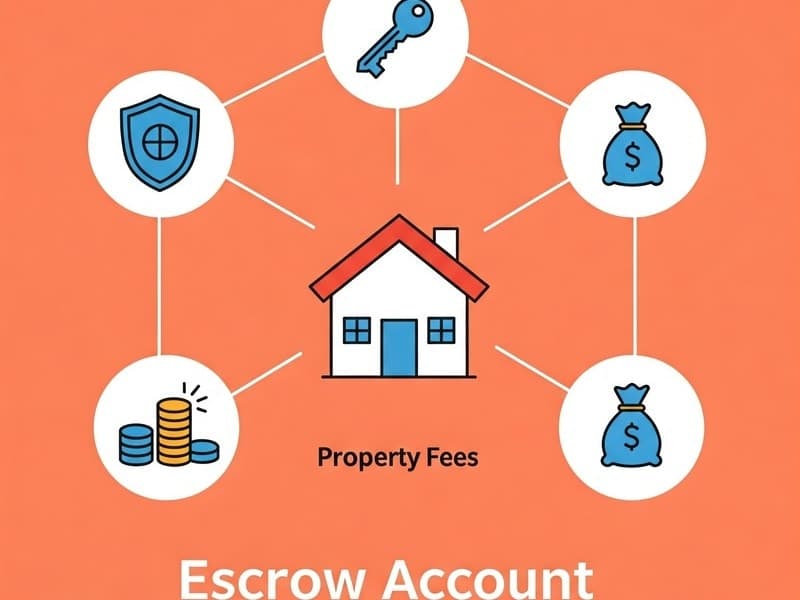
Some mortgage lenders in Dubai set up escrow accounts where:
- You deposit part of your monthly payment
- Lenders use it to pay insurance & property fees on your behalf
This helps avoid large lump-sum payments and ensures nothing is missed.
Finding the Best Deal on Home Loans
Compare offers from several lenders on the interest rate, loan term and fees together, not on the headline rate alone. A bank with a slightly higher rate and no processing fee can cost less over a three year fixed period than one with a low rate and a 1% fee. Ask each lender for its Key Facts Statement and put the offers side by side. A mortgage broker can do that comparison for you.
How to Use a Mortgage Loan Calculator Dubai the Smart Way
- Choose a calculator from a reputable bank or broker site
- Input:
- Property price
- Down payment
- Loan term (up to 25 years)
- Interest rate
- Add estimated monthly fees:
- Municipality Housing Fee
- Service charges
- Insurance premiums
- Review the full monthly cost, not just principal + interest
- Separate one-time costs (DLD, registration) and plan them into your savings
Work with a mortgage broker Dubai to help compare rates and plan smarter.
FAQs: What Dubai Buyers Want to Know
How much does a home loan cost in Dubai?
On a AED 1.5 million home with a 20% deposit, a AED 1.2 million loan over 25 years at 3.9% costs about AED 6,270 a month, plus about AED 1,150 a month in municipality fee, service charges and insurance. You also need about AED 382,000 in cash upfront, and total interest over the term is about AED 680,000.
How much cash do I need upfront for a home loan in Dubai?
Plan for the deposit plus roughly 5% to 6% of the price in fees: the 4% DLD fee, mortgage registration, the bank processing fee, valuation and trustee charges. The founder of mortgage broker IAH Group advises having 25% to 30% of the property value ready in cash (Khaleej Times, July 2026). Agent commission is extra.
Is there property tax in Dubai?
No direct annual tax, but DLD fees, registration fees, and service charges apply.
How can I calculate my real monthly mortgage payment?
Use a home loan calculator Dubai that lets you factor in fees and insurance, or add the service charge, municipality fee and insurance to the principal and interest figure by hand.
Is home insurance mandatory in Dubai?
Only if you have a mortgage, but it’s highly recommended even without one.
What is the minimum down payment to buy property in Dubai?
It depends on who you are and what you buy:
- Resident expats, first home: 20% up to AED 5M, 30% above AED 5M
- Second home or investment property: 40%
- Off-plan: 50%
- UAE Nationals, first home up to AED 5M: 15%
Why is the loan-to-value (LTV) ratio important in mortgage calculations?
The LTV ratio is the share of the price the bank will lend, and it sets your minimum deposit. Banks weigh it with the loan amount, interest rate and tenure to judge whether you can afford the mortgage.
Where can I find a trusted mortgage broker in Dubai?
Start with licensed brokers, check reviews, and ask for a free consultation.
Real Example: Monthly Budget Breakdown for AED 1.5M Property
The assumptions: 20% down (AED 300,000), a AED 1.2 million loan over 25 years at 3.9%. The service charge, municipality fee and insurance lines are illustrative and change from building to building.
| Component | Amount (AED) |
| Mortgage Payment (P&I) | 6,270 |
| Municipality Fee | 625 |
| Service Charges | 375 |
| Home Insurance | 150 |
| Total | 7,420 AED/month |
See the difference? That’s 1,150 AED/month beyond your mortgage payment. Over 25 years, the AED 1.2 million loan at 3.9% also carries about AED 680,000 in interest.
Cash needed on day one for the same property
The same AED 1.5 million purchase needs cash before you get the keys. Fees below are estimates: the bank processing fee assumes 1% of the loan and the valuation fee a mid-range AED 3,000.
| Item | Amount (AED) |
| Deposit (20%) | 300,000 |
| DLD transfer fee (4%) | 60,000 |
| Mortgage registration (0.25% of loan + 290) | 3,290 |
| Bank processing fee (1% of loan) | 12,000 |
| Valuation fee | 3,000 |
| Trustee office fee (4,000 + 5% VAT) | 4,200 |
| Total, before agent commission | 382,490 |
That is about 25.5% of the price. Agent commission, typically 2% plus VAT, would add another AED 31,500. Fixed rates from Dubai banks run roughly 3.75% to 5% in 2026, so see our comparison of fixed and variable home loan interest rates in Dubai before you pick the rate to use in your own sums.
Budget Smarter, Buy with Confidence
Owning property in Dubai is a milestone, but it’s also a financial commitment.
Using a mortgage calculator Dubai the right way means factoring in every hidden cost, not just the loan repayment. With the help of a mortgage loan calculator Dubai, plus a good mortgage broker Dubai, you’ll be able to buy property in Dubai without surprises, and with confidence. If this is your first purchase, our guide to entering the Dubai market as a first time buyer covers the steps in order.
Ready to take the next step? Contact Splendor.ae to start your home purchase with expert financial insight.